

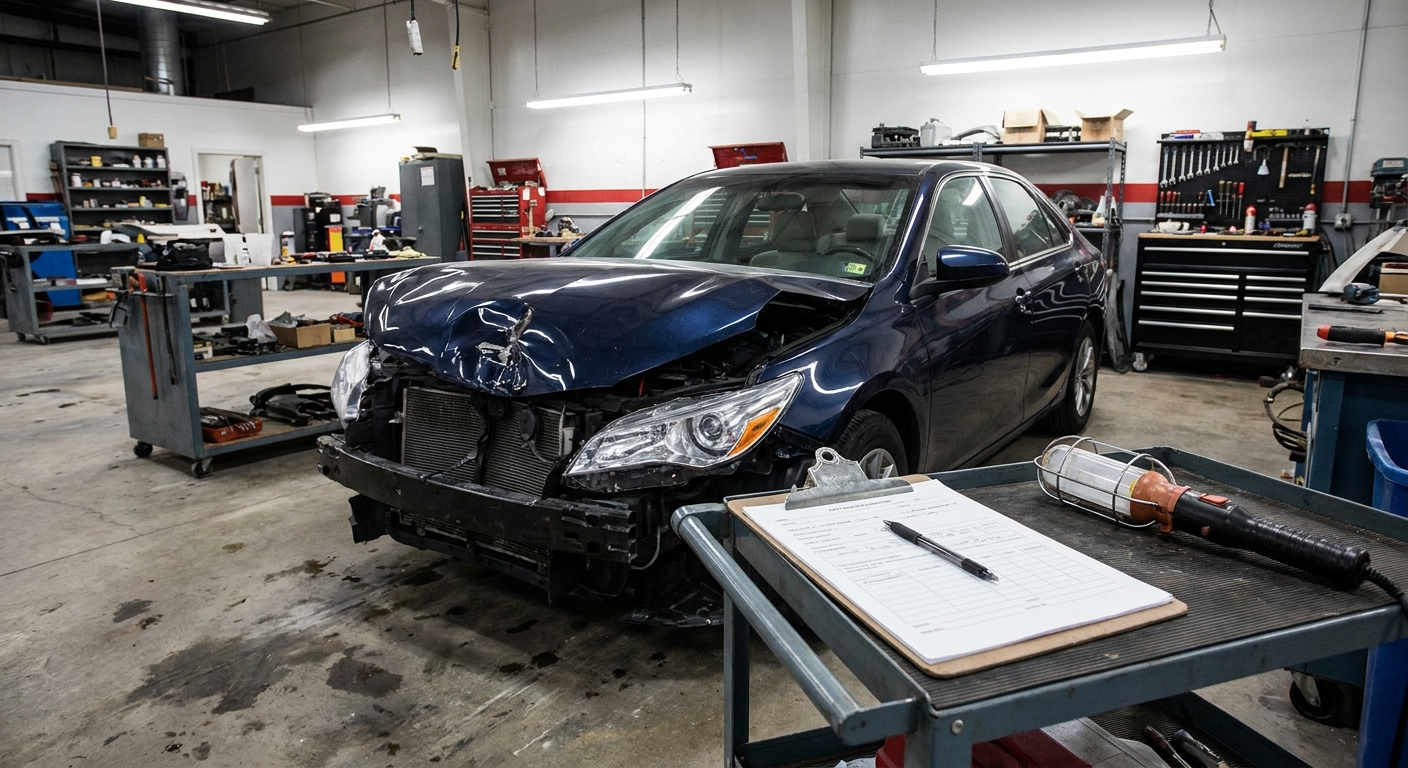
Your car is a total loss in California when the cost to repair it, plus its salvage value, meets or exceeds its actual cash value (ACV) just before the crash. Unlike some states that use a flat percentage, California uses this “total loss formula,” so whether your car gets fixed or totaled comes down to real numbers. Here is how it works and what your options are if the insurer calls it a total loss.
How does California decide a car is a total loss?
California applies the Total Loss Formula (TLF): if the cost of repairs plus the salvage value is greater than or equal to the actual cash value, the vehicle is a total loss. In plain terms, if fixing the car costs about as much as (or more than) the car is worth, the insurer “totals” it and pays you its value instead of repairing it. California does not use a fixed percentage threshold the way some other states do.
What is actual cash value (ACV)?
ACV is what your specific car was worth right before the accident, its year, make, model, mileage, condition, options, and local market all factor in. It is not what you paid or what a new one costs. Insurers use valuation tools and comparable local sales to set it, and this number is usually where disagreements arise.
Repair vs. total loss: a simple view
| Situation | Outcome |
|---|---|
| Repairs + salvage < ACV | Insurer repairs the car |
| Repairs + salvage ≥ ACV | Total loss; insurer pays ACV |
| Borderline | Hidden damage found in teardown can tip it to a total loss |
What happens if your car is totaled?
The insurer pays you the ACV (minus your deductible on a first-party claim), and the car’s title becomes salvage. You can usually choose to keep the vehicle by taking the payout minus the salvage value, but a salvage title has consequences for future registration and resale. If you still owe more than the ACV on a loan, gap insurance, if you have it, covers the difference.
What if you disagree with the total-loss decision or value?
- Ask for the insurer’s valuation report and the comparable vehicles used.
- Provide your own comps, recent maintenance, and condition documentation.
- A detailed repair estimate from a trusted shop can show the car is repairable, or confirm it is not.
- You can negotiate the ACV; the first offer is not always the final number.
How a body shop fits in
A thorough shop estimate matters on borderline cars. Hidden structural damage found during teardown can push a “repairable” car into total-loss territory, while a complete, accurate estimate can also support repairing a car the insurer was quick to total. Either way, you want the decision based on a full assessment, not a quick glance.
Frequently asked questions
Does California use a percentage to total a car?
No. California uses the Total Loss Formula: repairs plus salvage value versus actual cash value.
Can I keep my totaled car?
Usually yes, by accepting the payout minus salvage value; the car then carries a salvage title.
What if I owe more than the car is worth?
Gap insurance covers the difference between the ACV payout and your remaining loan balance, if you carry it.
The bottom line
In California, a total loss is a math question: repairs plus salvage versus actual cash value. Get a complete repair estimate, review the insurer’s valuation, and push back with your own comps if the ACV looks low. A careful body-shop assessment helps make sure a repairable car is not totaled, and an unsafe one is not patched up.
0 Comments